How to Stack Credit Cards and Maximise Every Dollar You Spend (2026)
Most Singaporeans pick one credit card and use it for everything. One card. Every transaction. Every month.
That's the single most common reason people leave hundreds of dollars in rewards on the table every year. Because no single card is the best card for every spending category. The banks designed it that way — each card rewards certain behaviours and punishes others. The moment you figure that out, you stop playing the game on their terms.
Card stacking is the fix. And in 2026, the right 3-card combination covers every dollar you spend — with no gaps, no overlap, and no mental overhead.
What Is Card Stacking?
Card stacking is the practice of using two or three cards strategically — each one assigned to the spending categories it rewards most generously. You don't spend more. You just earn more on what you're already spending.
The goal is simple: make sure every transaction lands on the card that pays you the highest rate for that category. Dining goes on the dining card. Groceries go on the groceries card.
Everything else goes on the catch-all card. Three cards, three roles, one system.
The 2026 RealisedGains Stack
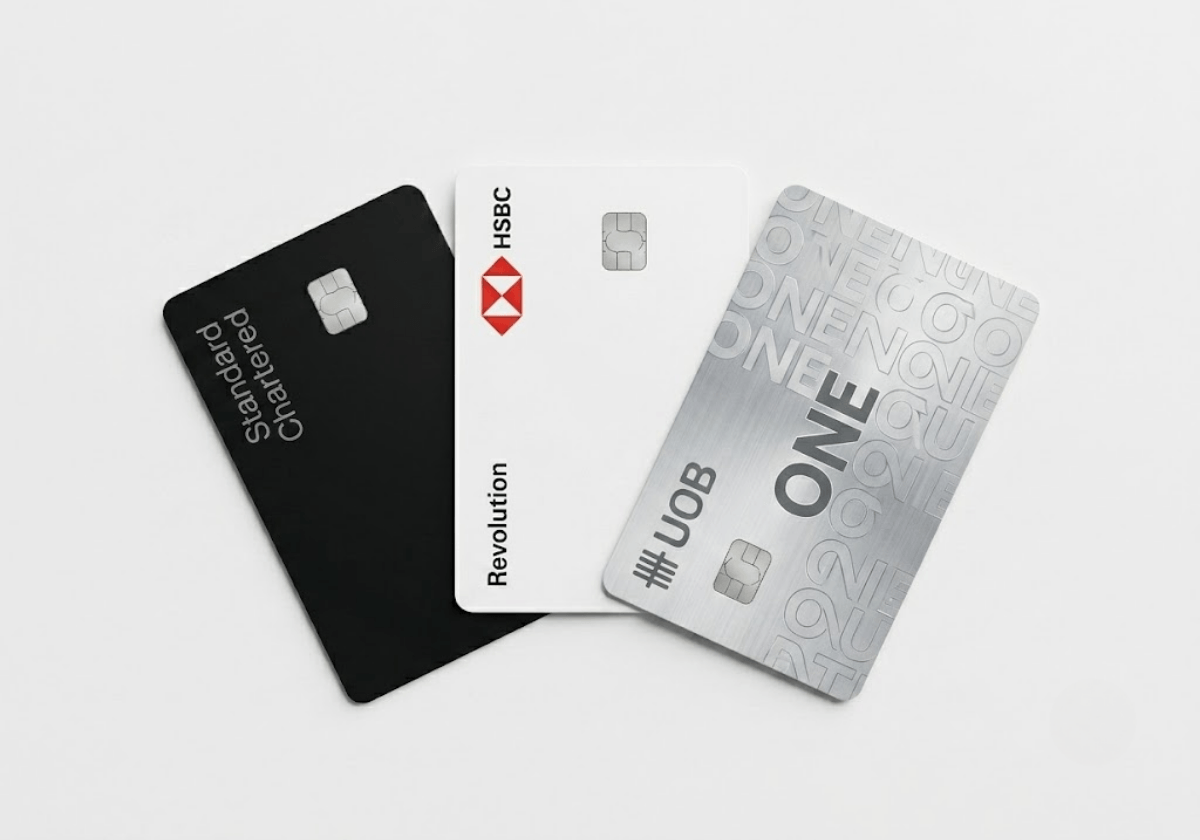
Based on current earn rates, fee structures, and how Singaporeans actually spend their money, here's the 3-card combination we recommend for 2026.
Card 1 — HSBC Revolution Card
Role: Dining, food delivery, online shopping, entertainment
The HSBC Revolution earns 10X points (equivalent to 4 miles per dollar) on dining, food delivery, online shopping, and entertainment — locally and overseas. That covers Grab Food, Deliveroo, Shopee, Lazada, Netflix, Spotify, and virtually every restaurant that accepts contactless payment.
The standout feature that makes this card non-negotiable in any stack: zero annual fee for life. Not waived for a year. Not conditional on minimum spend. Gone, permanently. This is the only card in Singapore's mainstream market with this guarantee — which means it costs you nothing to hold it indefinitely as part of your stack.
No minimum spend required to earn the 10X rate. No cashback cap eating into your rewards. Just points on every dining and online transaction, every month, without tracking anything.
💳 Earn rate: 10X points on dining, delivery, online & entertainment
✅ Annual fee: S$0 — forever
📋 Min. spend: None
Card 2 — UOB One Card
Role: Groceries, transport, utilities, Grab, Shopee
The UOB One is built for the spending that happens every single week regardless — supermarket runs, Grab rides, SimplyGo transport, utilities bills, and Shopee orders. Up to 10% cashback on these categories when you hit the monthly spend threshold and transaction count.
The key discipline this card requires: hit S$500–2,000 in monthly spend across at least 5 transactions, consistently, every month of the quarter. One weak month drops your rate to 0.3% flat. But for the Singaporean who is already spending on these essentials predictably — and that's most people — the UOB One pays more on groceries and daily spending than any other card in the market right now.
The 20% welcome promo for new UOB customers (valid until 30 September 2026) makes this one of the highest-value entry moments to pick this card up.
💳 Earn rate: Up to 10% on groceries, transport, utilities & Grab
✅ Min. spend: S$500–2,000/month across 5+ transactions
📋 Cashback: Calculated quarterly, capped at S$200/quarter at top tier
Card 3 — Standard Chartered Simply Cash Card
Role: Everything else — the catch-all
Every stack needs a catch-all — the card that earns on every transaction the other two don't cover. Insurance premiums. Government payments. Medical bills. Department store purchases. Any merchant that doesn't fall neatly into dining or groceries.
The SC Simply Cash earns 1.5% cashback on almost everything with no minimum spend, no cap, and no exclusion list to memorise. Spend S$4 at a hawker centre — 1.5% back. Pay a S$2,000 dental bill — 1.5% back. Book a hotel in local SGD — 1.5% back.
It does the one thing most cashback cards refuse to do: reward you for the awkward spending that falls outside every bonus category. And it does it consistently, month after month, without any tracking required.
💳 Earn rate: 1.5% on almost all spend (2% uncapped with S$800/month)
✅ Annual fee: S$192.60 (waived first year)
📋 Min. spend: None for 1.5% rate
The Full Stack — Side by Side
3 Cards. Every Category Covered.
No overlap. No gaps. No spending category that earns less than it should.
| Card | Use It For | Reward Rate | Annual Fee |
|---|---|---|---|
| HSBC Revolution | Dining · Delivery · Online · Entertainment Grab Food, Deliveroo, Shopee, Lazada, Netflix, restaurants | 10X points (4 mpd) | S$0 forever |
| UOB One | Groceries · Transport · Utilities · Grab FairPrice, Cold Storage, SimplyGo, SP bills, Shopee | Up to 10% cashback | S$196.20 (yr 2+) |
| SC Simply Cash | Everything else Insurance, medical, government, department stores, anything uncategorised | 1.5% uncapped | S$192.60 (yr 2+) |
How to Run the Stack Day to Day
The biggest reason people abandon card stacking is decision fatigue. They can't remember which card goes where, they pull out the wrong one, and eventually go back to using one card for everything.
The fix is simple: assign each card a physical or mental slot and never mix them up.
Put the HSBC Revolution on Apple Pay or Google Pay as your default mobile wallet — it earns on all contactless dining and delivery automatically. Keep the UOB One as your physical card for supermarket runs where you're tapping at the checkout anyway. And set the SC Simply Cash as the saved card for every recurring bill, insurance premium, and online checkout where the other two don't apply.
Once the habits are set, the stack runs on autopilot. You stop thinking about it. The rewards just stack.
The One Rule That Makes or Breaks the Stack
Pay your balance in full. Every month. No exceptions.
Card stacking only works in your favour if you are not paying interest. A single month of carrying a balance on any of these cards will cost you more in interest charges than three months of accumulated rewards. The math is brutal and it works entirely against you.
Set each card to GIRO auto-payment for the full outstanding amount. Do it when you apply for the card. Never think about it again. That one step protects everything else the stack earns for you.
The Verdict
One card is convenient. Three cards — the right three cards — is a system.
The HSBC Revolution handles your dining and online life. The UOB One handles your household essentials. The SC Simply Cash catches everything that falls through the gaps.
Together, they ensure almost every dollar you spend is earning at the highest available rate for that category.
Set it up once. Run it on autopilot. And stop leaving money on the table every month.
Shaun
Founder
RealisedGains is committed to empowering retail investors to achieve lasting financial well-being. By delivering meticulously curated investment insights and educational programs, RealisedGains equips individuals with the knowledge and tools to make sophisticated, informed financial decisions.
Founder, Analyst
With over a decade of expertise spanning investment advisory, investment banking analysis, oil trading, and financial advisory roles, RealisedGains is committed to empowering retail investors to achieve lasting financial well-being. By delivering meticulously curated investment insights and educational programs, RealisedGains equips individuals with the knowledge and tools to make sophisticated, informed financial decisions.
How to Stack Credit Cards and Maximise Every Dollar You Spend (2026)
© 2026 RealisedGains | All Rights Reserved | www.realisedgains.com
The go to platform that keeps you informed on the financial markets. Best of all, it's free.
The go-to platform that keeps you informed on the financial markets.
© 2026 RealisedGains | All Rights Reserved | www.realisedgains.com